Investing in mutual funds is a popular way to build wealth over time, but choosing the right plan can make a difference to your long-term returns. When you invest in a mutual fund in India, you may see two options: Direct Plan and Regular Plan. Both belong to the same mutual fund scheme, but they differ in cost and the type of support available to investors.
So, which option can help you save more money? A Direct Plan generally has a lower expense ratio, while a Regular Plan includes distribution costs and offers access to a mutual fund distributor. The better choice depends on your investment knowledge, comfort with making decisions, and need for guidance.
What Is a Direct Mutual Fund Plan?
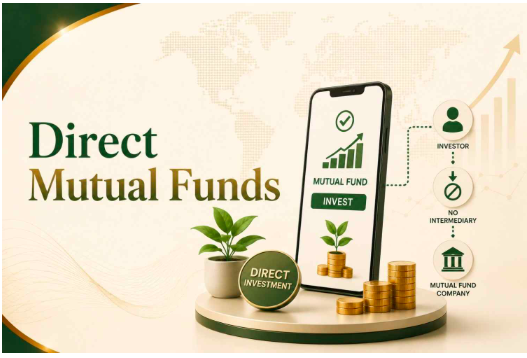
A Direct Mutual Fund Plan allows you to invest in a mutual fund scheme without using a mutual fund distributor or agent. You can usually invest directly through the asset management company (AMC) or an eligible investment platform that offers direct plans.
Since there is no distributor commission included in the plan's expenses, the expense ratio is generally lower than that of the corresponding Regular Plan. Lower ongoing costs can help improve the amount that remains invested and compounds over time.
Key features of Direct Plans:
Lower expense ratio compared with the corresponding Regular Plan.
Same underlying portfolio and fund manager as the Regular Plan of that scheme.
No mutual fund distributor involved in the investment.
You are responsible for researching funds and managing your investment decisions.
May suit investors who understand mutual funds and are comfortable investing independently.
What Is a Regular Mutual Fund Plan?
A Regular Mutual Fund Plan is purchased through a mutual fund distributor or agent. The distributor may help you understand fund options, complete the investment process, and provide ongoing assistance, depending on the service offered.
The scheme's expenses include distribution-related costs, so its expense ratio is generally higher than that of the corresponding Direct Plan. This additional cost can affect returns over the long term.
Key features of Regular Plans:
Investment support through a mutual fund distributor.
Higher expense ratio than the corresponding Direct Plan.
Same underlying scheme portfolio and fund manager as the Direct Plan.
Can be useful for investors who prefer help with fund selection and transactions.
The quality and extent of guidance may vary by distributor.
Direct vs Regular Mutual Funds: Key Differences
Feature | Direct Plan | Regular Plan |
|---|---|---|
How you invest | Without a distributor | Through a mutual fund distributor |
Expense ratio | Generally lower | Generally higher |
Distributor commission | Not included as a distribution commission in the plan | Distribution commission is reflected in scheme expenses |
Portfolio | Same underlying scheme portfolio | Same underlying scheme portfolio |
Fund manager | Same for the corresponding scheme | Same for the corresponding scheme |
Investor support | You handle your investment decisions | Distributor may provide assistance |
Long-term cost | Usually lower | Usually higher |
Best suited for | Investors comfortable researching funds independently | Investors who value distributor support |
The main difference is the cost of distribution, not the underlying investment portfolio. Both plans are exposed to the market risks of the same scheme.
How Do Direct Mutual Funds Save More Money?
The Direct Plan's lower expense ratio means less of your investment is used to cover ongoing scheme expenses. The difference may look small in a single year, but it can become more significant over a long investment period because investment costs affect compounding.
For example, consider an illustrative investment of ₹5,000 per month for 20 years.
Illustrative SIP comparison
₹5,000 Per Month for 20 Years
See how investment costs may affect long-term value
Direct Plan
₹32.4 Lakh Estimated investment valueRegular Plan
₹30.3 Lakh Estimated investment valueDisclaimer: This is a simplified illustration, not a prediction or guaranteed saving. Actual returns and expense ratios can change. Real SIP outcomes depend on market performance, cash-flow timing, scheme expenses and other factors. Mutual fund investments are subject to market risks.
Why Does the Expense Ratio Matter?
The expense ratio is the annual cost of running and managing a mutual fund scheme, expressed as a percentage of its assets. It is deducted from the scheme's assets and reflected in its net asset value (NAV).
Even a small cost difference can matter for three reasons:
Longer investment periods: Costs continue to affect your investment year after year.
Compounding: Money lost to expenses cannot generate future returns for you.
Larger investments: A percentage-based cost difference can have a bigger rupee impact as the amount invested grows.
However, a lower expense ratio does not guarantee positive returns. The value of both Direct and Regular Plans can rise or fall with the market.
Advantages and Disadvantages of Direct Plans
+ Advantages
− Disadvantages
Advantages and Disadvantages of Regular Plans
+ Advantages
− Disadvantages
Which Is Better for Beginners?
A Direct Plan is not automatically the best choice for every beginner. If you can research mutual funds, understand risk, choose schemes that match your goals, and manage your portfolio independently, a Direct Plan may be a cost-effective option.
If you need ongoing help understanding fund choices or managing your investments, a Regular Plan may be more appropriate. You should compare the value of that support with the additional cost. You can also consider getting advice from a SEBI-registered investment adviser, who generally charges separately for advice.
The important point is to choose a suitable fund and investment strategy first. Saving on expenses is useful, but it cannot make an unsuitable or excessively risky investment appropriate for you.
How to Choose Between Direct and Regular Mutual Funds
Before investing, consider these practical steps:
Check your investment knowledge. Understand the fund's objective, risk level, portfolio, and investment horizon.
Compare the expense ratios. Check the latest Direct and Regular Plan costs on the fund house's official website.
Review your need for support. Decide whether you are comfortable researching and managing investments on your own.
Compare the same scheme. Make sure you are comparing the Direct and Regular versions of the same mutual fund, not two different funds.
Think about your long-term goals. Your choice should fit your financial goals, risk tolerance, and investment timeline.
If you already hold Regular Plans, do not switch automatically just to reduce expenses. Check the tax implications, any applicable exit load, and other consequences before making a change.
Conclusion
Direct Mutual Funds generally save more money on ongoing expenses, which can make a difference to long-term investment outcomes. However, Regular Plans offer access to distributor support that some investors find valuable.
The right choice depends on your ability to manage investments, your need for guidance, and the additional cost you are willing to pay. Compare the two plans carefully, understand the risks, and choose the option that best supports your financial goals.
FAQ'S
Direct Plans generally have lower expenses, while Regular Plans offer access to distributor support. The right choice depends on your needs.
Direct Plans may deliver higher net returns than corresponding Regular Plans because their expense ratios are generally lower. Returns are not guaranteed.
They may suit beginners who value distributor assistance with fund selection and investment transactions.
You can generally switch, subject to the scheme's procedures. Check possible capital gains tax and exit loads before making the change.
Yes. Direct and Regular Plans of the same scheme generally share the same underlying portfolio and fund manager, but their expenses and NAVs differ.
Who should use Business & Finance
Direct vs Regular Mutual Funds: Which Saves More Money? is built for travelers, shoppers, students, and small teams comparing values across currencies. The main goal is clearer estimates before purchases, invoices, budgets, or travel planning, so the guide focuses on practical choices instead of broad theory.
Use it when you need one of these outcomes:
- checking a price before buying from another country
- estimating travel budgets and daily spending
- comparing invoice or subscription values across currencies
How to get a better result
- Enter the amount and currency pair you want to compare.
- Check when the rate was last refreshed or updated.
- Add expected card, bank, or marketplace fees to the estimate.
- Use the result as guidance, not as a guaranteed final bank rate.
Start small, check the first output, and only then repeat the workflow with the full file, text, media, or game session. That gives you a quick quality check before you spend more time.
Quality checks before you trust the output
- the rate is fresh enough for the decision you are making
- fees, bank margins, and taxes are considered separately
- large transfers are verified with your provider before payment
Do not use a converter result as a final trading, tax, or transfer quote. Real payments can include spreads, delays, and provider-specific fees.
Continue your workflow
If you want to try the workflow now, open the related AltFTool tool area. For more reading, continue through the Business & Finance archive or the AltFTool finance guide archive.
This creates a cleaner path from explanation to action: read the guide, test the tool, compare the output, and move into the next related AltFTool resource only when it helps the task.
Sources and review notes
References used to check facts, freshness, and reader-safe recommendations in this guide.
This content is for educational purposes only and is not investment advice. Mutual fund investments are subject to market risks.
- 1AltFTool https://www.altftool.com/
altftool.com
Discussion
0 comments
No comments yet
Discussion will appear here once it loads.