
General Liability Insurance
Helps address certain third-party injury and property damage claims related to business operations.
Explore insurance options designed to help small businesses manage common risks, protect their property, and support the people and operations that keep their business running.
Review policy types that can be tailored around how your business operates.
Coverage needs often depend on your industry, location, and day-to-day risks.
Explore liability, property, people, vehicles, and digital risk protections.
Requirements and availability can vary by state, contracts, and business type.
Education
Small business insurance refers to a range of insurance policies that can help businesses manage financial risks associated with property damage, customer injuries, professional claims, employee injuries, vehicles, cyber incidents and other business-related risks.
Different businesses need different combinations of coverage. A restaurant, contractor, consultant, and home-based shop can face very different day-to-day exposures—so options should be reviewed around operations, location, and eligibility.

Key idea
Coverage is not one-size-fits-all. The right mix depends on your business, state, contracts, and risk profile.
Coverage library
Browse commonly considered policy types. Availability, limits, exclusions, and pricing vary by insurer, state, and business circumstances.
Helps address certain third-party injury and property damage claims related to business operations.

Combines commonly paired coverages such as general liability and commercial property into one package.
Can help protect business buildings, equipment, inventory, and certain other property from covered losses.

Designed to help address claims alleging errors, omissions, or professional service mistakes.

May help with medical costs and lost wages for employees injured on the job, subject to state rules.

Can help cover vehicles used for business purposes, including liability and physical damage options.

Helps businesses respond to certain cyber incidents such as data breaches and related response costs.

May help replace lost income if covered property damage forces a slowdown or temporary shutdown.
Industry explorer
Every industry faces distinct exposures. Select your business type to see commonly reviewed policies and tailored risk protections.
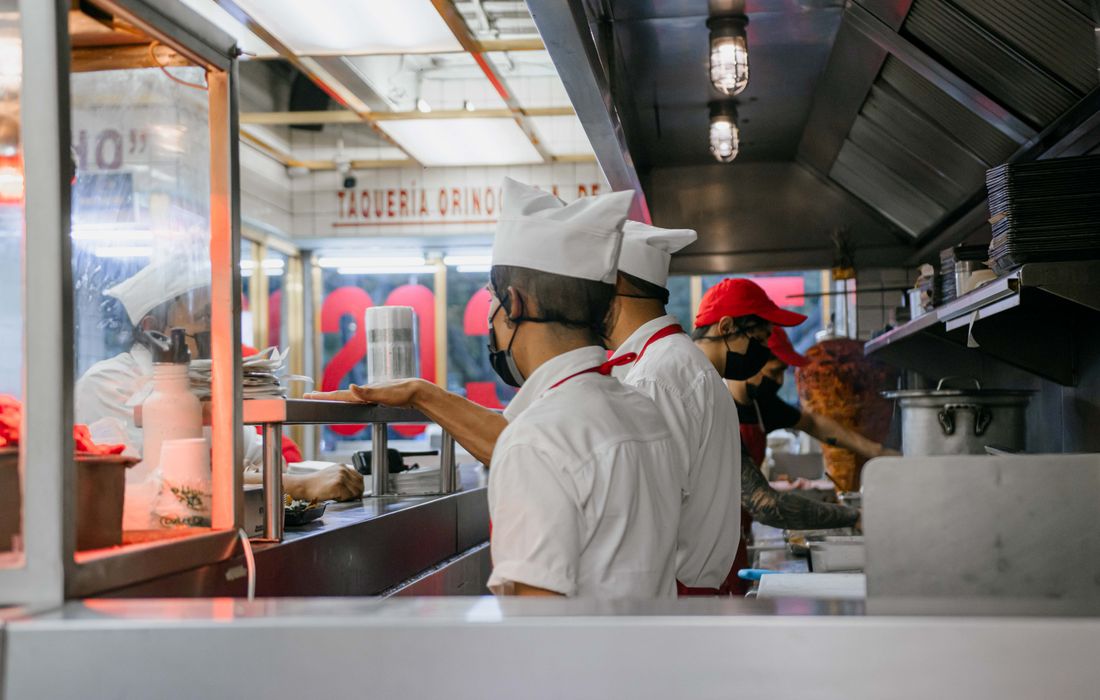
Food-service businesses often evaluate customer-facing liability, property, and employee-related coverages.
Core Protection Plan
Business Owner's Policy (BOP)
A Business Owner's Policy (BOP) packages essential property and liability protections together, often saving businesses money compared to purchasing standalone policies separately.

Bundled Policy Package
Combines essential small business coverages into one simplified, cost-effective policy.
Helps address customer injury, bodily injury, and property damage claims arising from daily business operations.
Protects owned or rented commercial buildings, specialized machinery, equipment, inventory, and business personal property.
Helps replace lost business income and ongoing operating expenses if a covered disaster temporarily halts your operations.
BOP eligibility and included endorsements vary by insurer and business classification. Optional coverages like Cyber or Hired Auto can often be attached.
Why businesses look at coverage
Insurance does not prevent every loss, but it can help businesses prepare for certain financial impacts when covered events occur.
Coverage options may help address certain losses involving buildings, equipment, inventory, and business personal property.
Liability policies can help respond to covered third-party claims involving bodily injury, property damage, or professional services.

Business income coverage may help replace lost income after a covered property event interrupts operations.

Workers' compensation and related coverages can help support employees after workplace injuries, subject to state requirements.
Restaurants, contractors, consultants, and retailers often face different exposures and may review different policy combinations.
Insurance is one tool businesses use to plan for events that could otherwise create significant unplanned expenses.
Interactive risk guide
Explore how common operational incidents and property perils are addressed by standard small business insurance policies.
Select a Risk Scenario
Auto-playing
A visitor slip, trip, or other injury on business premises can lead to medical and legal expenses. Related coverage often reviewed: General Liability.
Primary Policy Protection
General Liability
This guide is educational. Actual claim payments are governed by policy limits, conditions, deductibles, and exclusions.
Simple 4-step process
From entering your basic business details to receiving matched policy options, the process is fast, straightforward, and transparent.

Share basic details such as business type, location, and team size so options can be better matched.

Review commonly considered coverages for your industry and the risks most relevant to your operations.

Look at policy types, limits, and structures that may fit your goals. Availability varies by insurer and eligibility.

Submit your information to request next steps. A licensed representative or carrier may follow up as applicable.
Get matched with trusted carriers and explore coverage tailored around your business risks.
Customer experiences
Real stories from entrepreneurs, contractors, and retailers who protected their businesses and teams.
“When an electrical surge knocked out our commercial espresso machines on a Friday, our Business Owner's Policy stepped in smoothly to help with repair costs and lost revenue. Having BOP and liability in one package saved our bakery.”

Seattle, WA
“Our general contractor demanded certificates of insurance with specific liability limits before giving us site access. Getting verified General Liability and Commercial Auto took hours instead of days.”
Austin, TX
“As a boutique tech agency dealing with client confidential data, enterprise clients won't sign without proof of Errors & Omissions and Cyber Insurance. The guidance helped us understand exactly what limit tiers we needed.”

Chicago, IL
“Operating a busy downtown storefront means customer slip-and-fall protection is crucial alongside property and contents coverage. Having crystal-clear policy explanations gave me real peace of mind.”
Boston, MA
“Covering our work crew and hauling trailers on the road was essential. Our agent helped us bundle commercial auto and liability with great seasonal flexibility.”

Denver, CO
“Opening our second wellness clinic meant strict lease requirements for liability and workers' compensation. Everything was processed digitally in record time.”

Miami, FL
“Participant liability and studio contents coverage were tailored specifically for our high-intensity gym. Fast support whenever we add new trainers.”

Phoenix, AZ
“Enterprise SaaS deals require rigorous cyber limits and proof of coverage. We got tailored tech E&O and data breach protection with zero hassle.”

San Francisco, CA
“When an electrical surge knocked out our commercial espresso machines on a Friday, our Business Owner's Policy stepped in smoothly to help with repair costs and lost revenue. Having BOP and liability in one package saved our bakery.”
Seattle, WA
“Our general contractor demanded certificates of insurance with specific liability limits before giving us site access. Getting verified General Liability and Commercial Auto took hours instead of days.”
Austin, TX
“As a boutique tech agency dealing with client confidential data, enterprise clients won't sign without proof of Errors & Omissions and Cyber Insurance. The guidance helped us understand exactly what limit tiers we needed.”
Chicago, IL
“Operating a busy downtown storefront means customer slip-and-fall protection is crucial alongside property and contents coverage. Having crystal-clear policy explanations gave me real peace of mind.”
Boston, MA
“Covering our work crew and hauling trailers on the road was essential. Our agent helped us bundle commercial auto and liability with great seasonal flexibility.”
Denver, CO
“Opening our second wellness clinic meant strict lease requirements for liability and workers' compensation. Everything was processed digitally in record time.”
Miami, FL
“Participant liability and studio contents coverage were tailored specifically for our high-intensity gym. Fast support whenever we add new trainers.”
Phoenix, AZ
“Enterprise SaaS deals require rigorous cyber limits and proof of coverage. We got tailored tech E&O and data breach protection with zero hassle.”
San Francisco, CA
Quote request
Share a few details to request next steps. This is a front-end quote request experience and does not generate a binding insurance quote.
Fill in your basic company details in under 2 minutes. We match your operational profile with verified underwriters across the country.
A+ Rated Carrier Network: Compare leading nationwide commercial providers.
Custom Endorsements: Specific policies for contractors, retail, tech, and services.
Zero Obligation: Review comprehensive price and coverage options freely.
Pricing context
Premiums can vary widely. There is no universal monthly price for every small business.
Your business profile influences your insurance cost. Carriers typically evaluate factors such as industry, location, payroll, property values, limits, and claims history before providing options.

Your business profile influences your insurance cost.
Request options based on your operations instead of relying on generic averages.
Business resources
Educational guides to help you understand common coverage concepts before you request options.

Coverage Basics
Learn what general liability typically addresses, what it may not cover, and why limits and endorsements matter.

Policy Packages
See how a BOP can package key coverages and why eligibility and included protections vary by insurer.
By Industry
Explore how restaurants, contractors, retailers, and consultants often approach coverage differently.
Professional Risks
Get a clear overview of errors and omissions coverage for advice- and service-based businesses.
FAQs
Clear answers to common questions about small business insurance in the United States.
Small business insurance refers to a range of policies that can help businesses manage financial risks tied to property damage, customer injuries, professional claims, employee injuries, vehicles, cyber incidents, and other business-related exposures. The right mix depends on your operations.
Many small businesses review general liability, commercial property, a business owner's policy, professional liability, workers' compensation, commercial auto, cyber insurance, and business income coverage. Not every business needs every policy.
A Business Owner's Policy (BOP) commonly packages general liability and commercial property, and may include business income protection. Availability, eligibility, and included coverages vary by insurer and business profile.
Not every business has the same requirements, but general liability is frequently considered—especially when you interact with customers, visit client sites, or sign leases and vendor contracts that request proof of coverage.
Premiums vary based on industry, location, employees, revenue, coverage limits, claims history, operations, and selected policies. There is no single monthly price that applies to every business.
Many states require workers' compensation when you have employees. Exemptions and rules differ by state, business structure, and worker classification. Check applicable requirements for your situation.
Use the quote form on this page to share your business type, location, employee count, coverage interests, and contact details. Submitting the form requests next steps—it does not generate a binding insurance quote by itself.
Join 12,000+ owners receiving monthly updates on state compliance requirements, coverage trends, and policy optimization tips.
